Plan a Trade
Build a structured setup and use practical trading tools before you act.
Trade IdeasRisk ToolsCalculators
BUILD A TRADE IDEA →
Plan trades, connect MT4 & MT5, review verified execution, explore traders and research brokers — without learning the whole platform first.
Build a structured setup and use practical trading tools before you act.
Use Browser Trading or turn supported Telegram signals into a structured trading workflow.
Explore CopyTrade Masters, review their records and choose your own risk settings.
Compare IC Markets and PU PRIME by rating, regulation, minimum deposit, platforms, spreads, and overall trading conditions.
Use the FXVNPro Broker Checker Chrome extension to quickly review broker trust signals, ratings, and safety information while browsing broker websites.

| Feature | IC Markets | PU PRIME |
|---|---|---|
| Rating | 7 | 6.8 |
| Minimum Deposit | $1 | $20 |
| Regulation | ASIC, CySEC | ASIC, FSA |
| Platforms | MT4, MT5 | MT4, MT5 |
| Spread | From 0.0 pips | From 0.1 pips |
Below is a detailed breakdown of fees, spreads, regulation, platforms, and real trading suitability to help you decide which broker fits your trading style better.
If you’ve ever watched a “tight spread” vanish the moment volatility hits, you already know the uncomfortable truth: broker choice isn’t just a branding exercise. It directly affects your trading costs, your fills, and how smoothly your strategy actually performs in live markets. So when traders ask “IC Markets vs PU PRIME— which broker is better?”, what they usually mean is: where will my money go when conditions get messy?
IC Markets (Broker A) and PU PRIME (Broker B) both offer MT4 and MT5, and both sit under familiar regulatory umbrellas. But the details matter—minimum deposit, spread structure, and how trading costs stack up over hundreds of trades.
Here’s the short version. IC Markets starts from $1 and advertises spreads from 0.0 pips, which is attractive if you test strategies or trade with lower capital. PU PRIME starts from $20 and typically lists spreads from 0.1 pips. That difference doesn’t sound huge on paper, but on real execution it can affect your edge—especially if you’re scalping or running tight stops.
Who should care most? Active traders, anyone trading around news, and beginners who don’t want their first attempts derailed by surprising friction. In the sections below, I’ll break down fees comparison, spreads and trading costs, regulation and safety, and the practical “how it feels” differences you’ll notice when you actually trade.
Let’s talk money, because this is where IC Markets vs PU PRIME becomes real. Both brokers mention “from” spreads—IC Markets from 0.0 pips and PU PRIME from 0.1 pips. Sounds simple, but the effective cost depends on how spreads behave during your trading hours and how commission (if any) is handled in your account type.
In real trading conditions, the spread you see on a website is rarely the spread you trade every minute. During quieter Asian sessions, spreads can look close to the advertised figure. Then you get London overlap or a news release, liquidity thins, and your average spread widens. That widening is what matters for P&L.
Here’s a practical example. Suppose you run a mean-reversion strategy with a 1.2 pip average move target and you take 200 trades a month. If one broker’s average cost is just 0.1–0.2 pips worse after typical widening, that can translate into a noticeable chunk of performance. It’s not dramatic on a single trade. Over time, it’s the difference between “almost there” and “I’m actually profitable.” This matters because your edge is usually thin enough already.
Hidden fees are also worth watching. Some brokers have swap/rollover structures, inactivity fees, or withdrawal frictions that only show up later. With these two, the big “daily” cost is spreads and trading costs, not some obscure one-time charge—so you should compare your account’s exact trading model (spread-only vs commission + spread) before you decide which one is cheaper for your style.
Bottom line for fees and spreads: IC Markets has a slight headline advantage with spreads from 0.0 pips, but the “cheaper” broker for you is the one that delivers the lowest average cost in the sessions you trade. Which is why you should sanity-check spreads over a week, not an afternoon.
Regulation sounds like a simple list—ASIC, CySEC for IC Markets; ASIC, FSA for PU PRIME. But traders rarely get burned because the logo on the website looked wrong. They get burned because of execution practices, account handling, or the way disputes are managed when something goes sideways.
ASIC and CySEC are generally well-known regulators in retail FX. They matter because they typically enforce rules around segregation of client funds, leverage limits, and conduct oversight. In plain language, stronger regulators usually reduce the chance that your account experience becomes “whatever the broker feels like today.” That doesn’t mean zero risk, but it does change the odds.
With PU PRIME, you also see ASIC and an FSA reference. Here’s where verification becomes important: “FSA” can refer to different entities depending on jurisdiction. Before you fund, check the broker’s registration details on the regulator’s website and confirm the exact legal entity behind your account. It’s boring work, but it’s the work that prevents unpleasant surprises.
In real trading, safety isn’t only about protection after a dispute. It’s also about how consistently your broker follows its own policies—margin rules, execution standards, and how they handle margin calls. If your strategy relies on tight risk control, inconsistent margin handling is a risk multiplier.
So which broker is safer? Based on the information provided, IC Markets looks stronger on the “recognized retail oversight” front because of ASIC and CySEC. PU PRIME may still be perfectly workable, but you should verify the specific FSA jurisdiction and entity details carefully. This is one of those “do it once, sleep better” checks.
Both IC Markets and PU PRIME offer MT4 and MT5, which is good news if you already have indicators, EAs, or a trading routine built around MetaTrader. Still, the platform isn’t the whole story. The user experience is shaped by execution speed, order handling, and how reliably the platform reflects what’s happening at the broker level.
In real trading, execution speed and slippage matter most when spreads are moving fast. If you’re placing limit orders during a trend and the market is slipping through levels, the difference between “it looked filled” and “it was actually filled at a worse price” becomes obvious. This matters because strategies with tight stops and fast exits can be hypersensitive to slippage.
MT4 vs MT5 also changes the workflow. MT4 is familiar, lighter, and still popular for EAs. MT5 can be better for certain charting, multi-timeframe analysis, and order types, but some traders find it slightly less comfortable for legacy systems. Neither broker forces you into one or the other—so your comfort level should guide your choice.
Tools and usability aren’t just indicators. It’s also about how stable the platform is under load, how quickly charts update, and how smooth order modifications feel during high volatility. If you’ve ever tried to adjust a stop after a spike and the platform lagged, you know what I mean.
With IC Markets, the combination of very low minimum deposit and a “from 0.0 pips” model typically appeals to traders who test tactics and refine execution. PU PRIME’s slightly higher spread headline and higher minimum deposit may be more comfortable for traders who already have a baseline account size and don’t want to micromanage execution as much.
If you rely heavily on automated trading, choose the broker that matches your EA’s assumptions and gives you the execution consistency you’ve measured—not what a brochure says.
Minimum deposit is one of those numbers that seems minor until you actually need to move money. IC Markets offers a minimum deposit of $1. PU PRIME requires $20. On the surface, that’s just “how much to start.” In practice, it affects how you build your trading confidence and how you test.
If you’re a new trader, a tiny minimum deposit can let you practice with position sizing, understand margin requirements, and learn how order tickets behave without risking a meaningful amount. That learning curve is real. People underestimate how long it takes to stop clicking wrong buttons.
For more experienced traders, deposits and withdrawals affect how often you can iterate. Maybe you want to test a new EA on a small run, then scale up if it behaves. With a $1 minimum, you can do that more easily. With $20, you can still test—but you’re committing more capital upfront.
Withdrawals matter too, even if you don’t think about them daily. The important questions are: how fast do withdrawals process, what fees are charged (if any), and how many steps or verification checks are required? A broker that’s smooth for deposits but slow or complicated for withdrawals can be a problem if you ever need funds quickly.
I’ll be careful here: without specific payment method data, I can’t claim one broker is faster across the board. But the friction you feel tends to correlate with verification flow and operational maturity, and those usually track with the broker’s overall structure.
In real trading, “friction cost” shows up indirectly. If you delay withdrawals, you might keep more money in the account than you intended. That changes your risk management. Again—small differences compound.
Purely on minimum deposit, IC Markets clearly gives more flexibility to test and refine. PU PRIME is still accessible, but it nudges you toward committing a bit more at the start.
Beginners don’t lose money only because of strategy. They lose money because of process. They overtrade, mis-size, break max loss rules, and sometimes misunderstand spread behavior around volatility. A broker can’t fix that—but the broker can either reduce friction or add to it.
IC Markets has a $1 minimum deposit and advertises spreads from 0.0 pips. That combination is beginner-friendly because it allows you to learn without feeling like you’re burning meaningful capital in the learning phase. You can practice placing orders, adjusting stops, and tracking your costs. You can also test whether your platform is stable for your daily routine.
PU PRIME’s $20 minimum deposit is not huge, but it’s still enough to make a cautious beginner hesitate. If your first week includes mistakes, that $20 becomes psychological weight. You start thinking about “not losing this” instead of focusing on building discipline.
Also, spreads and trading costs matter for beginners because they often trade more frequently while they’re still learning. If your spread costs are slightly higher, it can turn small stop-outs into a frustrating spiral. In other words, the broker’s execution environment affects how forgiving the market is when you’re not yet.
Now, regulation and safety matter here too. Beginners need a broker where policies are predictable. IC Markets’ ASIC and CySEC presence is a reassuring baseline, while PU PRIME requires a bit more verification attention around the exact FSA entity tied to your account.
So which is better for beginners? Based on what we have, IC Markets edges it for low-cost learning and lower initial friction. PU PRIME can still work, but you’ll likely feel the minimum deposit and spread reality sooner.
Active traders don’t just want “tight spreads.” They want consistent execution speed, low average costs, and order handling that doesn’t fall apart during fast market moves. This is where IC Markets vs PU PRIME becomes more than a spreadsheet comparison.
IC Markets advertises spreads from 0.0 pips and has a very low minimum deposit, which often attracts scalpers and day traders who run many trades. For them, even tiny cost differences matter because the number of entries and exits is high. If your system targets, say, 1–2 pips frequently, then average spread and slippage become the real battleground.
PU PRIME lists spreads from 0.1 pips and a $20 minimum deposit. That’s not automatically worse—0.1 pips is small. But in practice, what you’ll notice is how quickly spreads widen when volatility spikes. Day traders typically trade around London and New York liquidity. That’s when spreads can behave differently across brokers even if both advertise “from” levels.
For execution, watch for slippage during market orders and the reliability of stop-loss placement. In real trading scenarios, the market doesn’t care about your backtest. You care about how your broker handles price changes between signal and fill.
Tools also matter for active traders. MT4/MT5 is the base layer, but the “active” experience includes whether the platform stays responsive, if order modifications are smooth, and if your charts reflect pricing without weird delays.
So which broker is better for active traders? If your strategy is sensitive to micro-costs and you want the best shot at low average spreads, IC Markets has the stronger setup on paper. PU PRIME may still be viable, but you should treat it like a broker you test—run your strategy for a week, measure actual spread and slippage, then decide.
IC Markets — Pros: very low minimum deposit ($1) for testing, spreads from 0.0 pips, MT4/MT5 support, and regulation includes ASIC and CySEC.
IC Markets — Cons: real trading costs depend on your account model and session volatility; “from 0.0 pips” doesn’t mean you’ll always trade at 0.0.
PU PRIME — Pros: regulation includes ASIC and an FSA reference, MT4/MT5 support, spreads from 0.1 pips can be fine for many day-trading setups.
PU PRIME — Cons: higher minimum deposit ($20) is less flexible for beginners and small testing cycles; you should verify the exact FSA entity tied to your account.
One more thing, and I mean this as a practical trader: don’t fall in love with the lowest headline spread. Fall in love with your measured average cost. That’s the number that shows up in your journal after 100 trades.
If you force me to answer clearly—IC Markets is the better choice for most traders in this head-to-head, mainly because of the combination of low minimum deposit and the more aggressive spread positioning. That matters for both learning and execution-sensitive strategies.
Choose IC Markets if: you want to start with minimal friction, you’re testing strategies or EAs, or you trade actively where spreads and slippage can make or break results. The “IC Markets vs PU PRIME” decision is easiest here because $1 minimum deposit gives you flexibility, and spreads from 0.0 pips give you a better chance at lower average trading costs.
Choose PU PRIME if: you’re comfortable starting at a $20 minimum, you’re not scalping micro-moves for dozens of trades per session, and you do your due diligence on the exact regulatory entity under the FSA reference. PU PRIME can still fit many day traders, but you should verify the details and test execution before you commit heavily.
For both brokers, the smart move is the same: check spreads and trading costs over the specific hours you trade, watch slippage during fast moves, and confirm the account type’s cost structure (spread-only vs commission-related). That’s how you turn “which broker is better” from a slogan into a decision.
In short: IC Markets is the cleaner pick based on the information you gave. PU PRIME isn’t a bad alternative, but it’s the one I’d approach with more verification and more testing.
One real XAUUSD trade: created before the outcome, sent to Telegram, executed in MT5 and returned as a verified result.
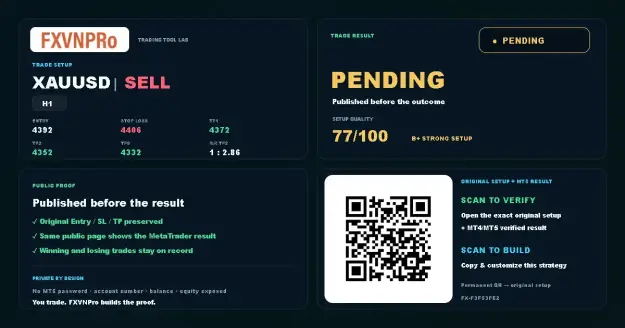 1 · SETUP
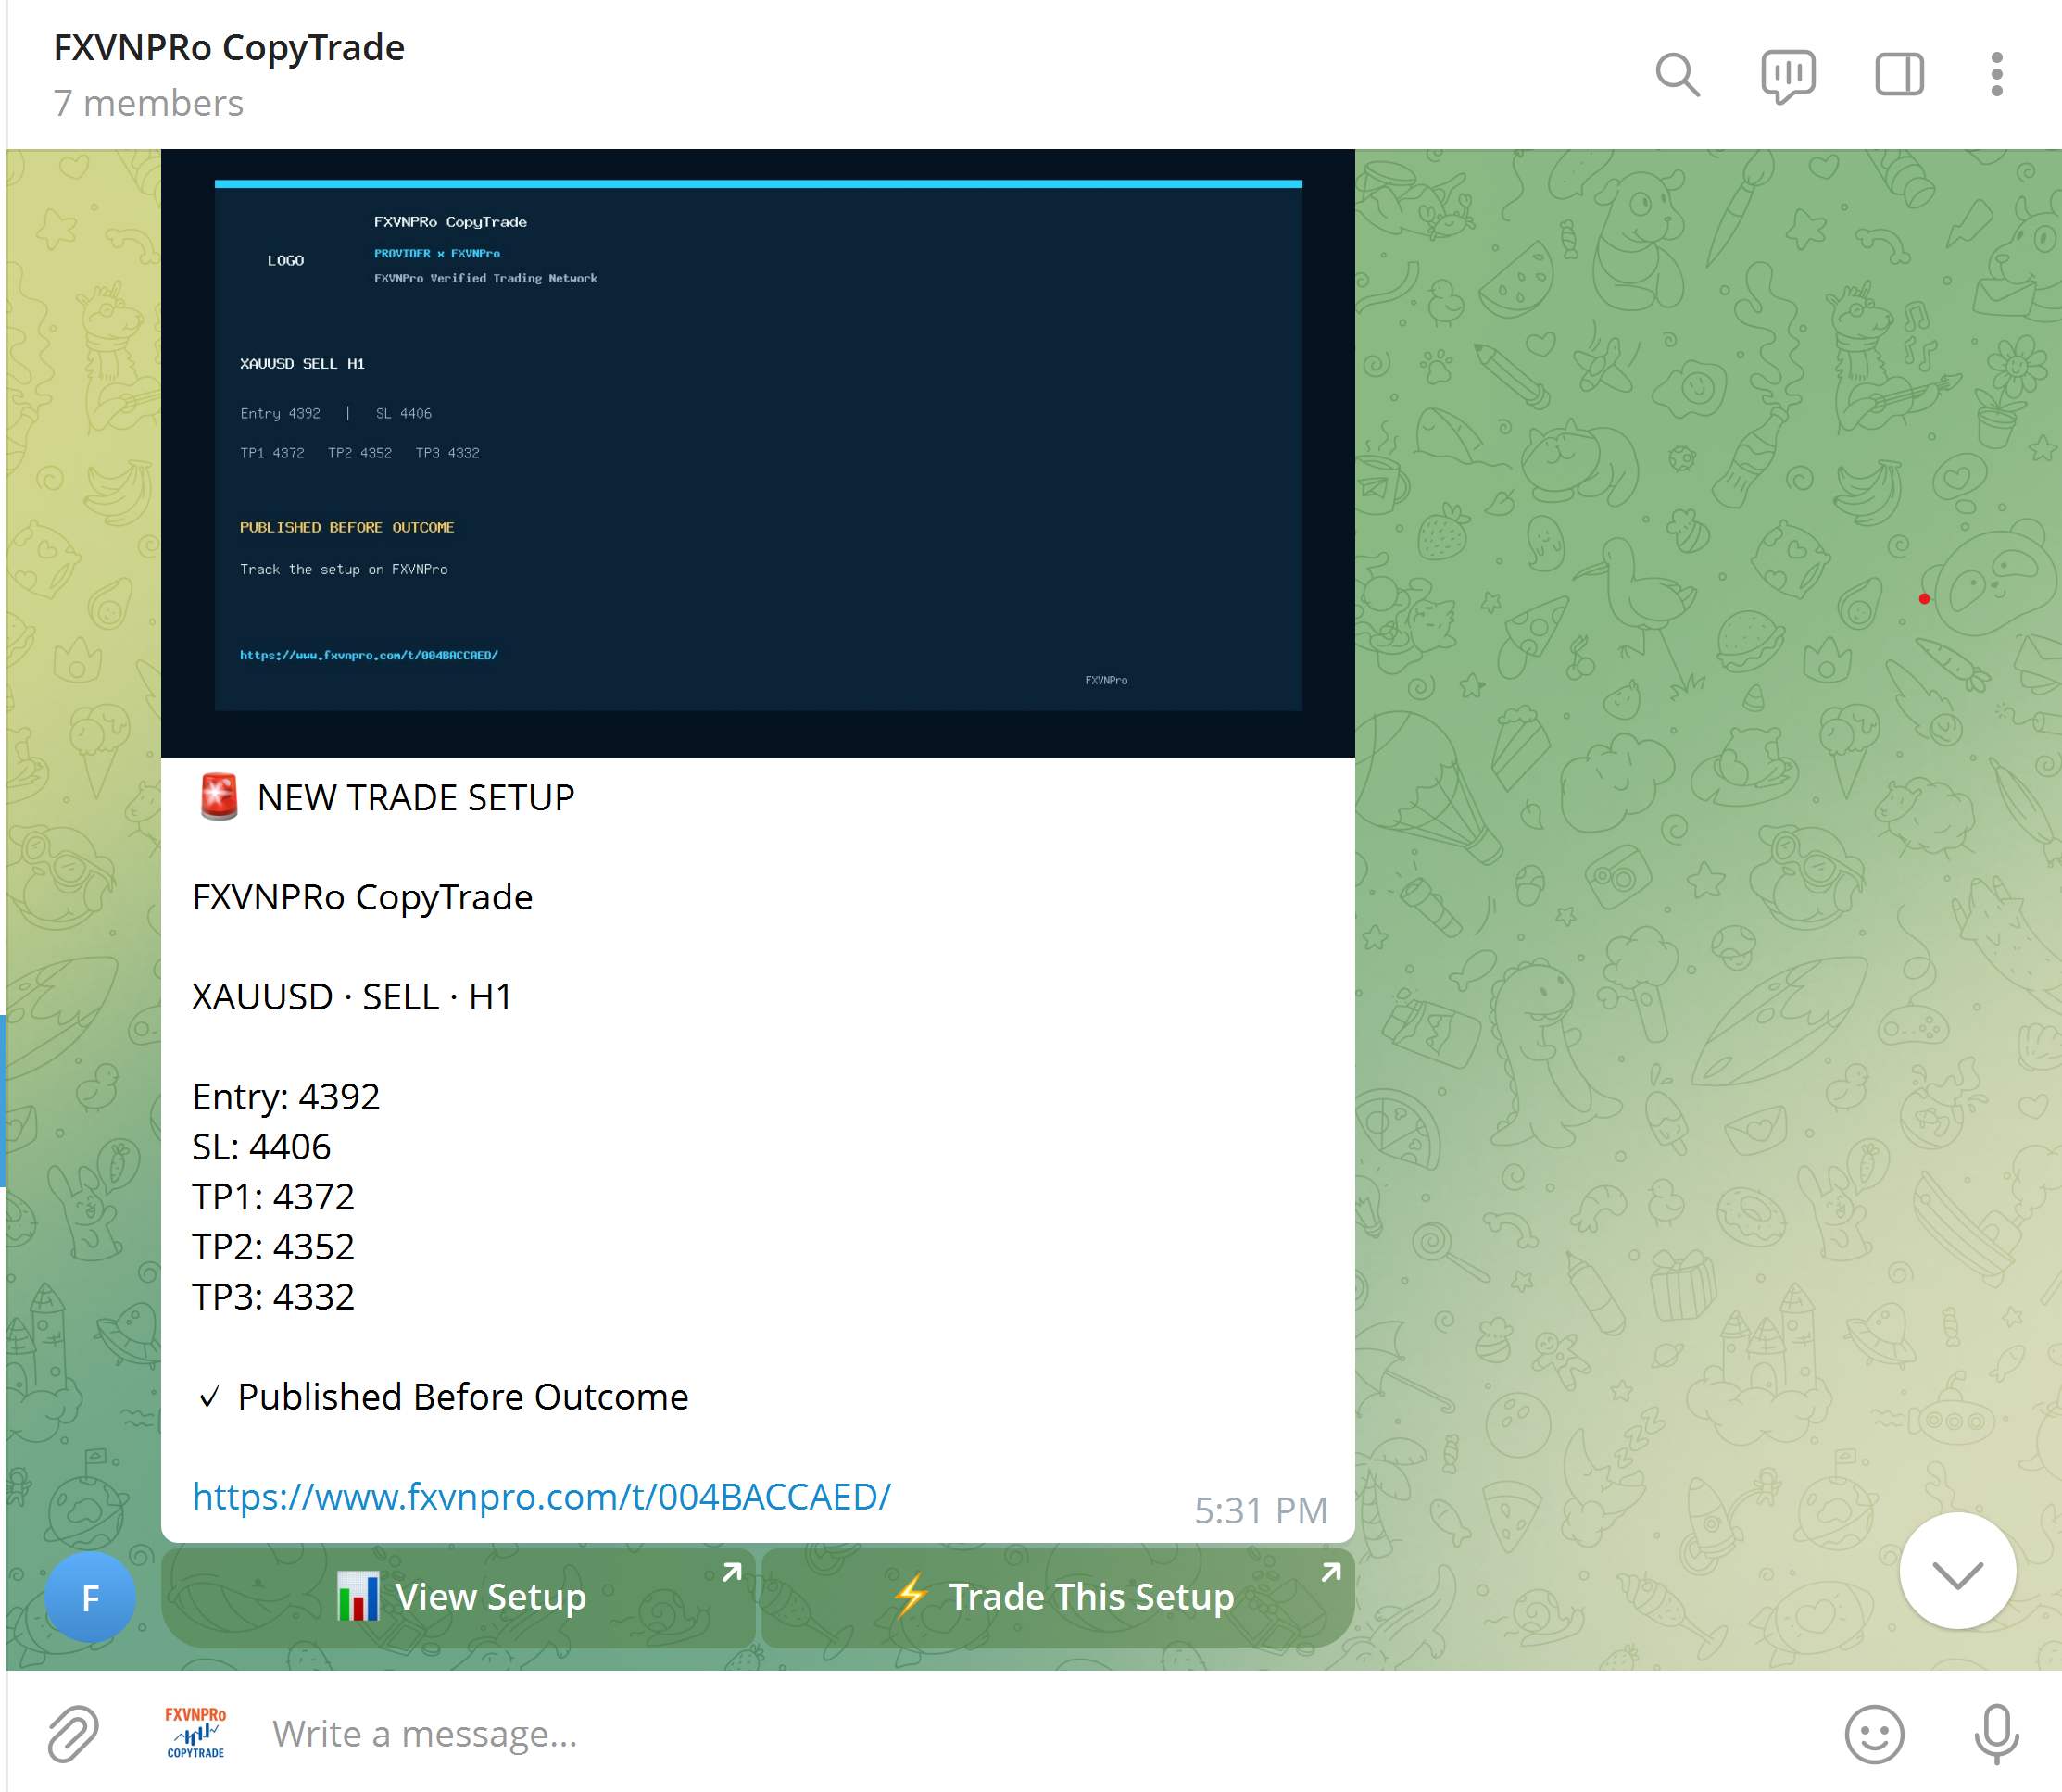 2 · TELEGRAM
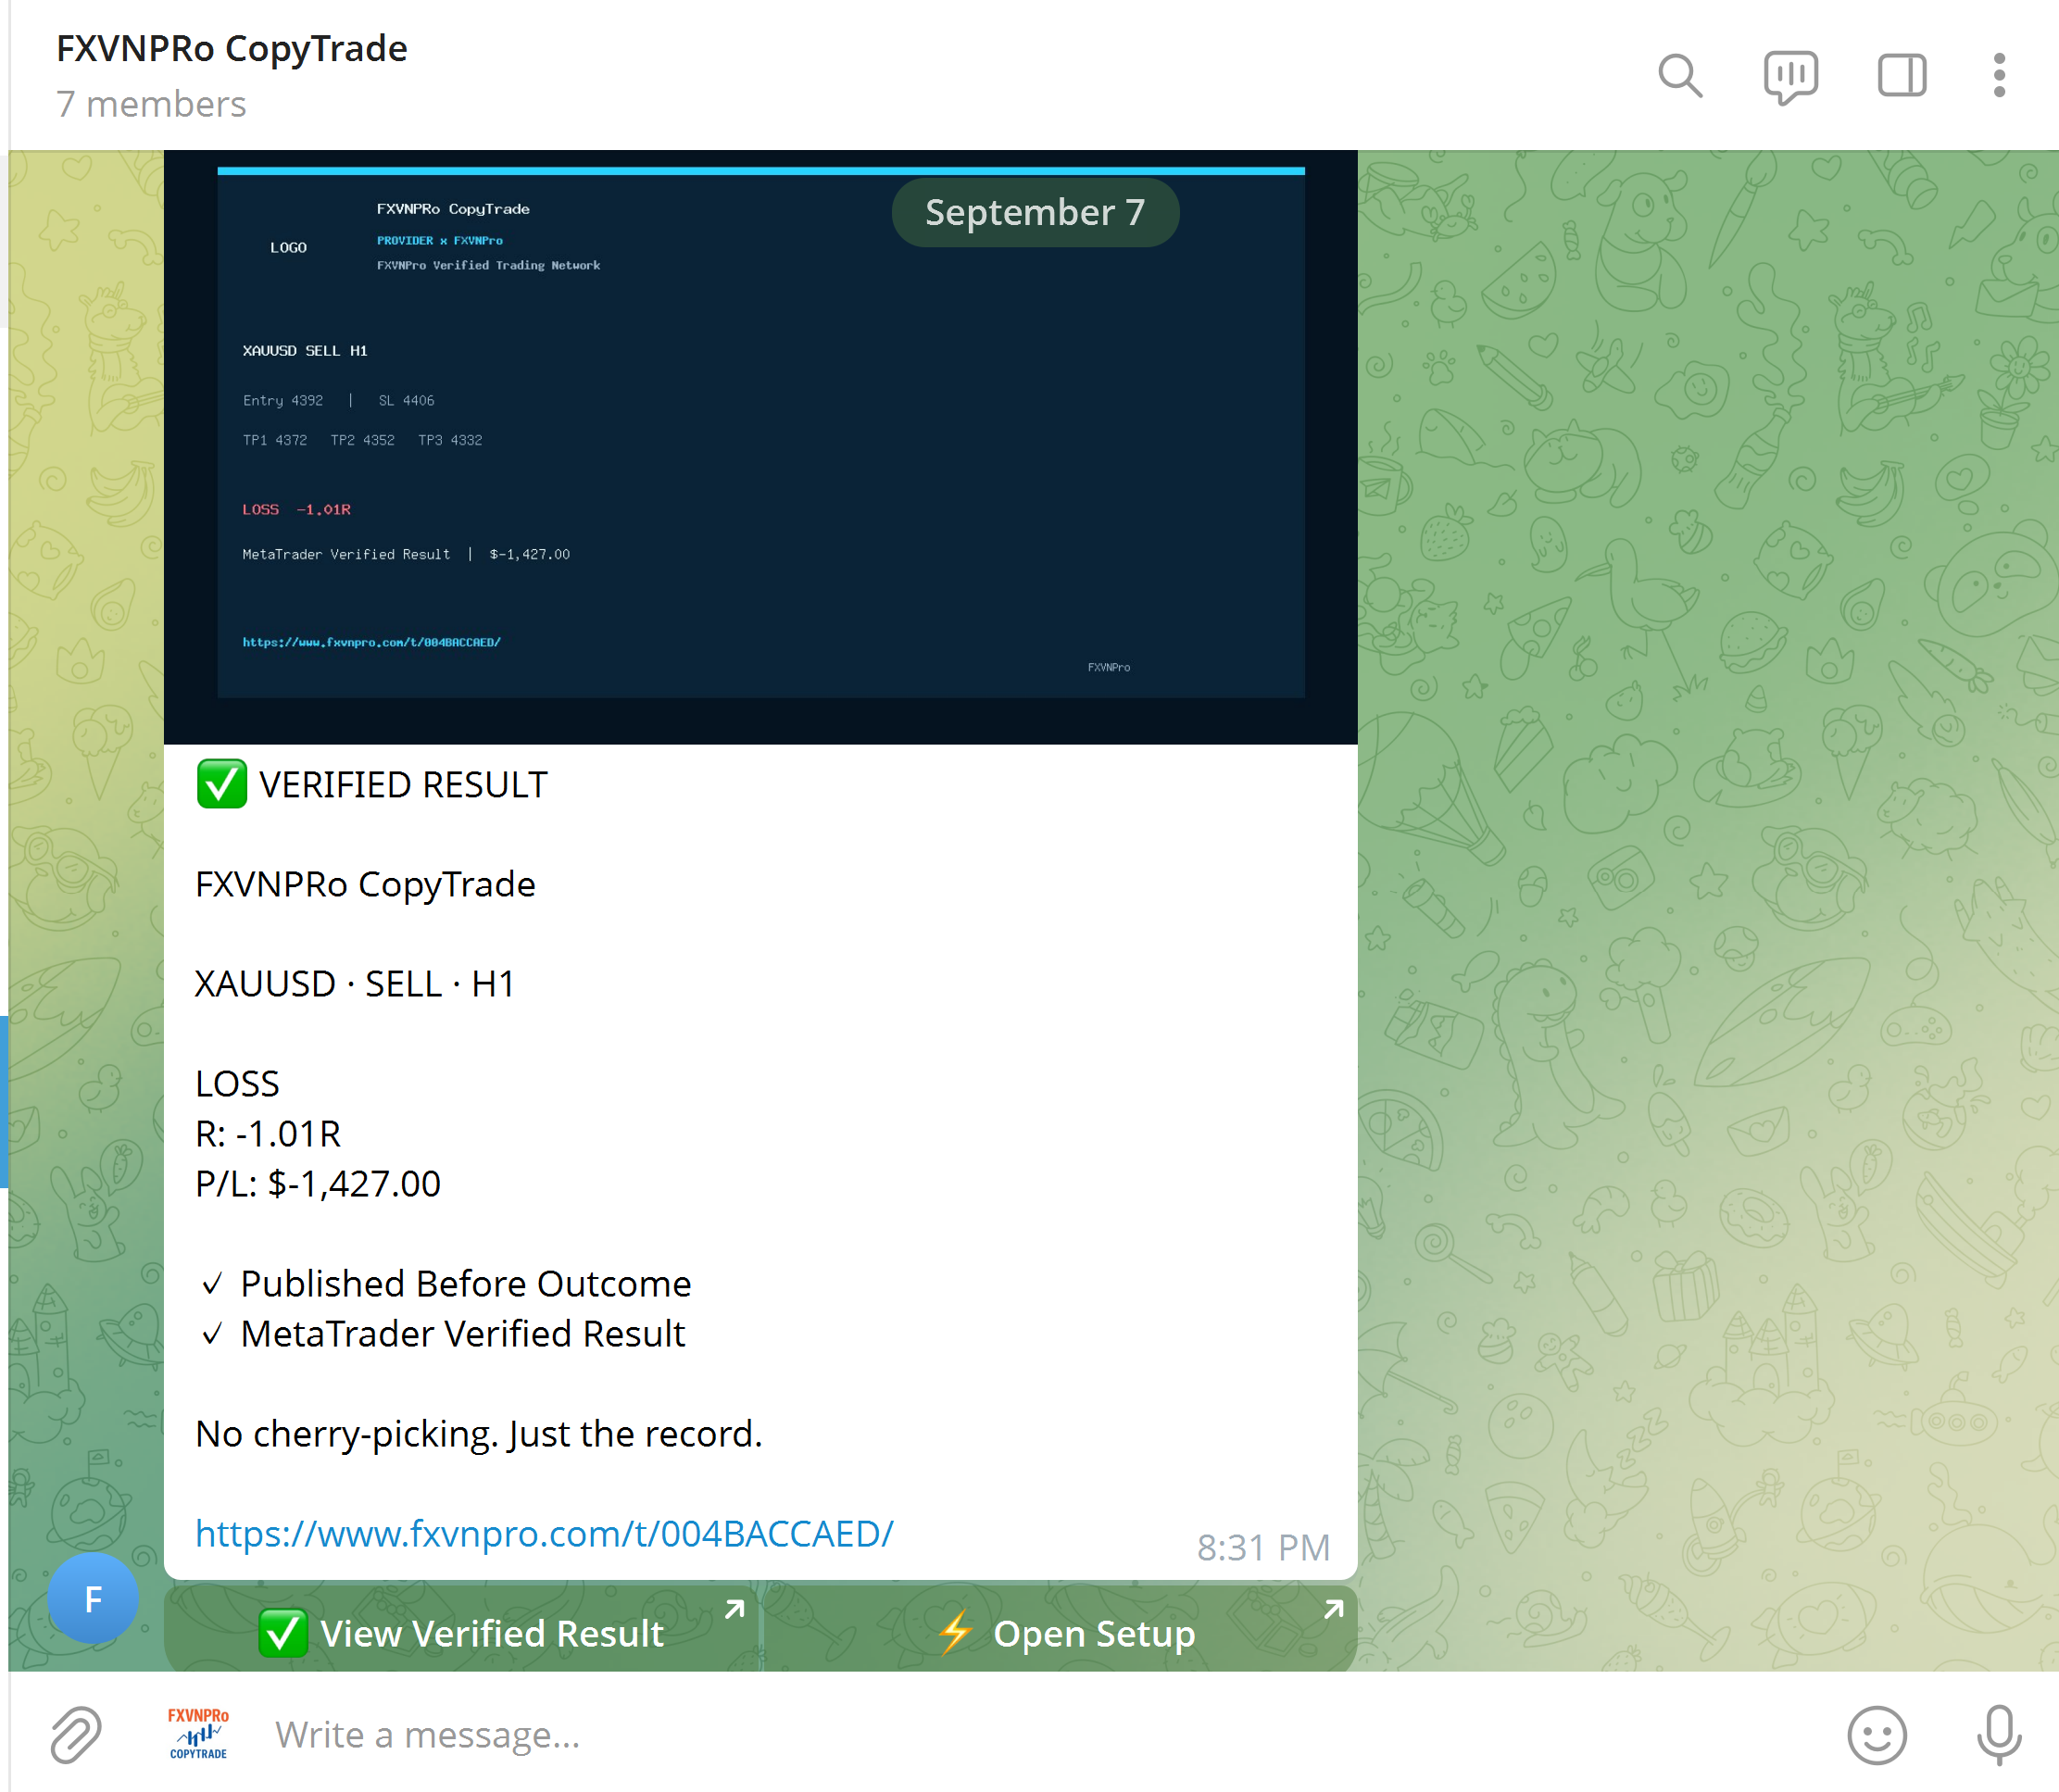 3 · VERIFIED
Build your strategy, distribute it to a community, or follow trading activity across MT4 & MT5.
Create Entry, Stop Loss and Targets before the outcome, then build a verified trading record.
Turn Telegram signals into an actionable workflow while followers keep control of their own risk.
Connect Chrome to MT4 or MT5 and open, modify or close trades from your browser.
Explore Masters and copy trading activity to your own MT4 or MT5 terminal with independent risk rules.
 GUIDE